Cryptocurrency in Divorce: How Is It Divided?
Cryptocurrency can be marital property even when only one spouse controls the wallet. Learn how to document holdings, address price swings, and choose a practical division method.
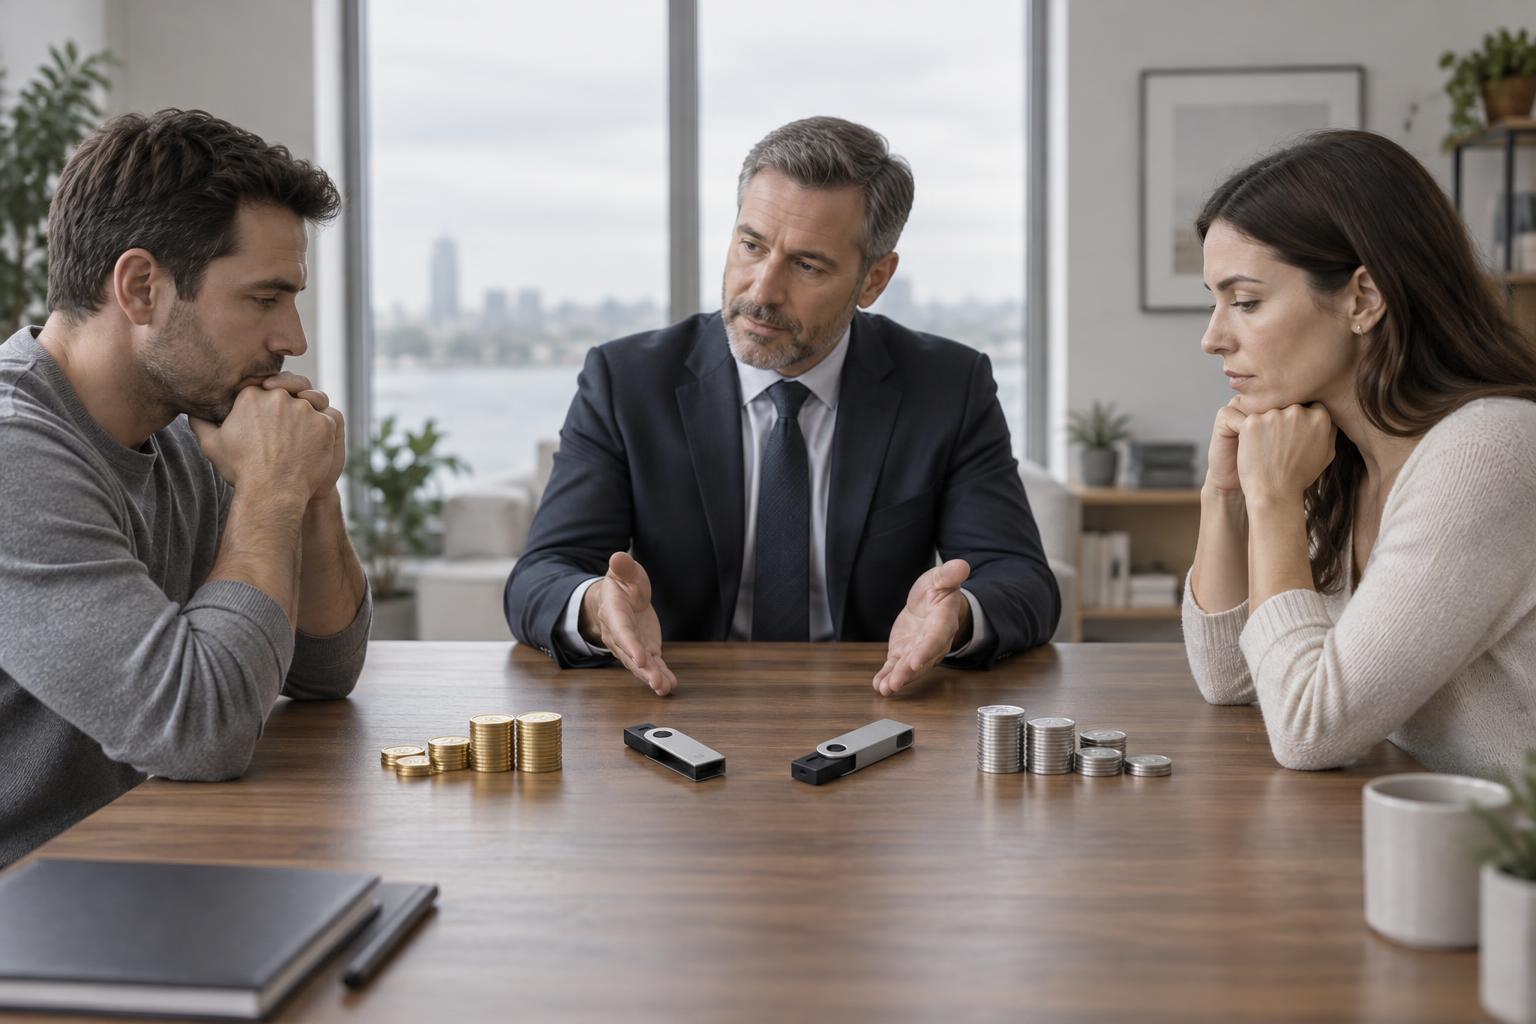
Cryptocurrency in divorce is generally divided under the same state property laws that apply to other assets: the marital or community portion is subject to division, while a proven separate-property portion may remain with its owner. A fair division requires identifying the holdings, determining their value, and choosing whether to transfer the cryptocurrency, sell it, or offset it with other property. Laws vary by state, so speak with a local divorce attorney before moving or trading disputed crypto.
Is cryptocurrency marital or separate property?
The name on an exchange account does not necessarily determine who owns its value in a divorce. Neither does possession of the password or private keys. Courts generally focus on when and how the asset was acquired, where the purchase funds came from, and the applicable state rules.
Cryptocurrency bought during the marriage with marital earnings will commonly be marital or community property. That can be true even if one spouse made every investment decision and the other never used the account.
Crypto owned before marriage, or received individually through a gift or inheritance, may be separate property. However, the spouse claiming that status generally needs records supporting it. A valid prenuptial or postnuptial agreement may also affect the outcome.
What if the account contains both types?
Suppose you owned Bitcoin before marriage, then bought more during the marriage using wages. One wallet could contain both separate and marital holdings. Moving everything into the same wallet does not automatically settle its classification; tracing the transactions becomes important.
Growth in separate-property value can also raise state-specific questions, particularly if marital labor or money contributed to that growth. Mining proceeds, staking rewards, and other crypto earnings deserve individual review rather than an assumption that they follow the original asset’s classification.
In community-property states, division generally follows community-property rules. In equitable-distribution states, the marital estate is divided fairly, which does not necessarily mean equally. Neither system necessarily requires splitting every coin down the middle.
What cryptocurrency records should you gather?
Start with an inventory, not just a screenshot of today’s balance. A current balance does not show whether assets were transferred elsewhere, purchased before marriage, or sold recently.
Useful records include:
- Exchange records: Account statements, transaction exports, trade confirmations, and account ownership information.
- Wallet information: Public wallet addresses, relevant blockchain networks, and transaction histories.
- Purchase records: Bank transfers, card payments, and documents showing the source of funds.
- Tax records: Filed returns, available tax forms, and crypto tax reports showing proceeds and cost basis.
- Other holdings: Stablecoins, NFTs, staking positions, decentralized finance investments, and claims against failed platforms.
- Access limitations: Withdrawal restrictions, lockup terms, pending unstaking requests, or documented lost access.
Download full transaction exports when available. Screenshots can supplement them, but often omit fees, timestamps, and transfers between accounts. Preserve original files and note when you obtained them.
A hardware wallet is a device used to manage access credentials; the cryptocurrency itself is recorded on a blockchain. Finding the device does not establish the holdings’ value, and possessing it may not provide access.
Do not put seed phrases, private keys, or passwords in ordinary financial disclosures or public court filings. Ask your attorney how to document ownership and arrange any necessary secure access without exposing assets to theft.
What if you suspect undisclosed crypto?
Crypto transactions can be difficult to interpret, but they are not necessarily untraceable. Many public blockchains record transfers openly. The challenge is connecting an address to a person and distinguishing genuine purchases or sales from transfers between that person’s own wallets.
Possible leads include transfers to exchanges, references to digital assets in tax records, and unexplained withdrawals. None proves concealment by itself. A transfer may represent an ordinary investment, an expense, or a move between disclosed accounts.
Use formal disclosure rather than self-help
Your attorney may request exchange statements, wallet addresses, transaction histories, and explanations through the divorce discovery process. Where legally available, records may also be sought directly from a platform. Overseas exchanges and decentralized services can present additional obstacles.
A forensic accountant or blockchain investigator may help when the amounts justify the expense. Ask what the expert can realistically establish, what records they need, and how they will avoid counting the same holdings more than once as funds move across wallets or networks.
Do not guess passwords, impersonate your spouse, install monitoring software, or enter accounts without authorization. Knowing an old password is not a reliable sign that access is legally permitted.
If you believe assets are about to disappear, contact your attorney promptly about lawful preservation measures. Concealment or violation of court orders can lead to sanctions or other remedies, depending on state law and the facts.
How is cryptocurrency valued for divorce?
For a widely traded token, a starting point is the number of units multiplied by a documented market price. But the parties still need to identify the asset correctly and agree on—or obtain a ruling about—the valuation date and method.
A useful valuation record specifies:
- The token and blockchain network, including the contract address when needed.
- The exact number of units held.
- The date, time, and time zone of the price quote.
- The exchange or pricing source used.
- Any restrictions, fees, or liquidity issues affecting realizable value.
State law and court practice influence which valuation date applies. Do not assume it is automatically the separation date, filing date, or settlement date.
What about volatile or hard-to-sell assets?
Bitcoin’s value can change substantially between negotiations and transfer. An agreement promising “$40,000 worth of Bitcoin” leaves questions about when the price is measured and who bears intervening gains or losses. A transfer of a specified number of units creates a different allocation of market risk.
NFTs, thinly traded tokens, and locked investments may require more than an app’s displayed price. A listing price is not necessarily a price a buyer will pay. Stablecoins can lose their peg, and balances on a failed platform may represent uncertain recovery claims rather than immediately available cash.
For significant or disputed holdings, an independent valuation may help. If access is allegedly lost, ask what evidence supports that claim before treating the holdings as worthless.
What are the practical ways to divide crypto?
The best method depends on each spouse’s comfort with crypto, liquidity needs, tax position, and ability to access the asset. Three common approaches are:
| Method | How it works | Main trade-off |
|---|---|---|
| Divide the cryptocurrency itself | Each spouse receives an agreed number or percentage of units | Both retain market exposure and need secure custody |
| Sell and divide proceeds | Holdings are sold, then net proceeds are allocated | Creates liquidity but may trigger taxes and transaction costs |
| Offset with other property | One spouse keeps crypto while the other receives different assets | Avoids a forced sale but requires careful valuation and tax comparisons |
Dividing the actual holdings
An in-kind division can reduce arguments about price changes because both spouses receive their allocated units. The agreement should still address rewards, fees, lockups, and market exposure between signing and delivery.
The receiving spouse needs a suitable account or wallet that supports the correct asset and network. Some exchanges restrict particular tokens or deposits. Sending to an unsupported network or incorrect address can cause an irreversible loss.
Selling or using an offset
If selling, specify who authorizes the sale, when it happens, how fees are handled, and how the proceeds and associated tax obligations will be addressed. Settlement language should be reviewed for consistency with actual tax reporting rules.
For an offset, compare more than headline balances. Crypto valued at $50,000 with a low tax basis is not necessarily economically equivalent to $50,000 in cash. Likewise, retirement funds may carry taxes and withdrawal restrictions. Consider after-tax value, liquidity, and risk before accepting an apparently equal exchange.
What tax issues matter when dividing cryptocurrency?
For federal income tax purposes, digital assets are generally treated as property. Selling crypto for dollars, swapping it for another cryptocurrency, or using it to pay for something can create a taxable disposition.
By contrast, a qualifying transfer between spouses or former spouses incident to divorce generally does not trigger immediate recognition of gain or loss. Exceptions and qualification rules apply, so have a tax professional review the proposed transfer rather than assuming every divorce-related movement is tax-free.
Tax basis follows the asset in qualifying transfers
In a qualifying nonrecognition transfer, the recipient generally takes the transferring spouse’s adjusted tax basis. The divorce-date market value does not automatically become the recipient’s new basis.
For example, if transferred crypto has an adjusted basis of $5,000 and is later sold for $20,000, the gain generally starts with the $15,000 difference, subject to applicable adjustments. Receiving it when it was worth $18,000 would not ordinarily erase the earlier appreciation.
Request acquisition dates, transaction fees, tax-lot records, and basis documentation with the transfer. A wallet transaction alone usually does not provide everything needed for future tax reporting.
Staking rewards, mining activity, and decentralized finance transactions can raise additional tax questions. A divorce agreement allocating a tax cost between spouses does not necessarily change who must report an item to the IRS.
What should your settlement say about the transfer?
“Split the crypto equally” is often too vague to implement safely. The settlement or court order should identify the holdings and provide a workable delivery process.
Ask your attorney to address:
- Assets covered: Named tokens, networks, quantities, and any related rewards or claims.
- Allocation: Exact units, a percentage of identified holdings, or a dollar-based formula with a defined pricing method.
- Timing: Transfer deadlines and treatment of assets that cannot yet be withdrawn.
- Costs and changes: Responsibility for fees and allocation of intervening rewards, gains, or losses.
- Verification: A secure method to confirm destination details and document completed transfers.
- Records: Delivery of transaction history and tax-basis information.
- Problems: What happens if a platform freezes withdrawals or a party fails to cooperate.
For a substantial transfer, discuss whether a small test transaction and qualified technical assistance are appropriate. Verify destination details through a trusted channel; do not rely solely on an unexpected email requesting a new address.
An agreement generally need not require handing over an entire seed phrase, which could expose unrelated holdings. Properly arranged transfers to a separately controlled wallet may be safer. Divorcesify provides general information, not legal representation; a local divorce attorney can help turn these details into enforceable terms.
Key takeaways
- Crypto can be divisible marital property even when only one spouse controls the account or wallet.
- Purchase dates, funding sources, and transaction records help distinguish marital from separate holdings.
- A useful valuation accounts for timing, liquidity, access restrictions, and price volatility.
- You can divide the units, sell and split proceeds, or offset crypto with other property.
- Preserve tax-basis records and use specific, secure transfer instructions reviewed by legal and tax professionals.
Frequently asked questions
Is cryptocurrency split 50/50 in a divorce?
Not necessarily. The marital or community portion is divided under your state’s property laws, and an equitable division may not be equal. Even when the overall division is equal, one spouse may keep the cryptocurrency while the other receives different assets. Proven separate holdings may be excluded from division.
Can my spouse claim cryptocurrency I bought before marriage?
Cryptocurrency purchased before marriage may remain separate property if you can document its ownership and source. However, later purchases with marital money, mixed transactions, or growth connected to marital contributions can complicate the analysis. State law and any valid marital agreement matter, so preserve the original purchase and transfer records.
Do I have to disclose crypto held in a private wallet?
A self-custody wallet generally does not exempt cryptocurrency from required financial disclosure. You may need to identify holdings and provide records even if no exchange controls them. Disclosure should not mean publishing your seed phrase or private keys; ask your attorney about secure documentation and any appropriate confidentiality protections.
Will transferring cryptocurrency to my ex trigger taxes?
A qualifying transfer incident to divorce generally does not trigger immediate federal gain or loss, but exceptions apply. The recipient generally receives the transferor’s adjusted tax basis rather than a new market-value basis. Selling crypto before dividing cash can have different consequences, so review the proposed sequence with a tax professional.
What happens if my spouse says the crypto wallet is lost?
Lost access does not automatically establish that cryptocurrency has no value or can be omitted from disclosure. Your attorney may seek purchase records, wallet addresses, transaction histories, and evidence supporting the claim. A qualified expert may help assess whether holdings remain visible or have moved, although visibility does not guarantee recoverability.
AI-assisted general information from Divorcesify. This article has not been represented as reviewed by a licensed attorney; confirm current local law before acting.
Find your state’s divorce rules · Explore divorce process guides · Prepare for your attorney consultation
Attorney advertising. Divorcesify is not a law firm, is not a lawyer referral service, and does not provide legal advice. Information on this site is general and may not reflect current law in your state. Using this site or submitting a form does not create an attorney-client relationship. Divorcesify matches visitors with independent, licensed attorneys who pay a fee to participate. We do not endorse or guarantee any attorney, and the choice of a lawyer is an important decision that should not be based solely on advertisements. Read full disclosures.
Get the Divorce Preparation Guide
Checklists, a post-divorce budget outline, and the questions to ask your first attorney — free.
Keep reading
Temporary Orders in Divorce: What They Do and How to Ask
Divorce can take time, but decisions about children, housing, and bills often cannot wait. Temporary orders can establish enforceable rules while your case moves forward.

Who Claims a Child on Taxes After Divorce?
The parent entitled to claim a child for federal tax purposes is not always the parent named in a divorce agreement. Learn how overnight stays, IRS Form 8332, and different tax benefits fit together.
How to File for Divorce in California: Step-by-Step
Filing for divorce in California starts with residency, court forms, and proper service—but those steps do not end the marriage. Follow this practical guide through disclosures, settlement options, and the final judgment.